Buying Your Second Hotel: How to Scale to a Portfolio
The systems an owner needs before the second hotel: financing you understand, managers who can run without you, one set of books and one recovery process.
Quick answer: Buying a second hotel is less about finding the deal and more about building the systems that let two properties run without you standing in both lobbies. Before you buy, line up financing you understand, a management plan for both hotels, centralized accounting and controls, and one standard way to find and recover lost revenue at every property.
How do you know you are ready for a second hotel?
You are ready when your first hotel runs to a standard without your daily presence and you can prove it with numbers. If the first property depends on you to close the month, chase direct bill or catch billing errors, a second one will divide that attention.
- A GM or lead manager who can make daily decisions without you.
- A month-end close that finishes on schedule. See the month-end close process.
- Written controls for cash, refunds, rate overrides and adjustments.
- Clean financials a lender can read without a long explanation.
- Reserves for the new hotel's PIP, working capital and surprises.
How does financing a second hotel generally work?
Most owners use a combination of equity and debt, and the right structure depends on the property, the lender and your own balance sheet. What follows is a general overview only; confirm terms and suitability with your lender, attorney and CPA.
Common sources include conventional bank loans, SBA-backed loans and, for larger deals, commercial mortgage lenders. The SBA's 7(a) program has a maximum loan amount of $5 million, and its 504 program finances major fixed assets such as buildings and land but cannot be used for working capital. Some owners also use equity from their first hotel, through a refinance or a partnership.
Whatever the source, lenders will look closely at your first hotel's performance as evidence you can run the second. Our guide to what hotel lenders look for explains the metrics.
What due diligence matters most on the second deal?
The same diligence as your first hotel, with one addition: how easily the new hotel fits into the systems you already run. A hotel on a different brand, PMS or accounting setup costs more to integrate.
Also ask how the second hotel changes your risk. A property in the same market as your first shares its demand drivers, which makes it easier to manage but concentrates exposure to one economy. A property in a new market spreads that risk but adds travel, new vendors and a GM you will see less often. Neither is wrong; decide deliberately.
Look past the trailing twelve months. Review the seller's receivables aging, OTA invoices, chargeback history and any crew or corporate contracts you will inherit. The hotel acquisition due diligence checklist walks through each area.
How do you build management capacity for two or more hotels?
Decide early whether you will self-manage, hire a regional manager or bring in a third-party management company. Each can work, but the choice drives your staffing, your technology and your role.
- Define what you will personally own (for example, capital decisions, banking and brand relationships) and what you will delegate.
- Hire or promote a GM for each property with clear targets and authority.
- Consider a shared role across properties, such as a controller or revenue manager, once you have two or three hotels.
- If you are considering outside management, read how to evaluate a hotel management company.
Why centralize accounting and controls early?
Centralizing accounting early gives you comparable numbers across hotels and one set of controls, which is what lets you spot a problem at one property before it becomes a pattern. It also makes lender reporting and tax preparation simpler.
- One chart of accounts across all properties.
- One close calendar and one reporting package.
- Standard approval limits for refunds, adjustments and write-offs.
- Bank reconciliations reviewed by someone other than the person who records deposits.
The hotel financial controls checklist is a good starting template. Your CPA can advise on entity structure and tax reporting across multiple properties.
How do you standardize revenue recovery across a portfolio?
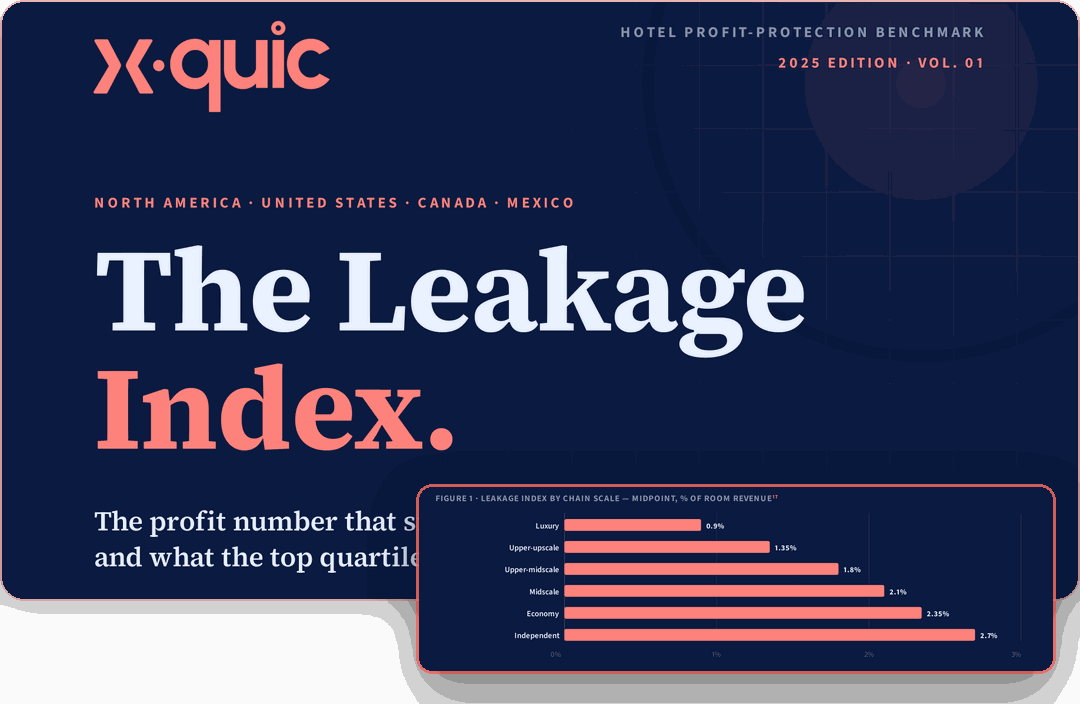
Use one process and one set of reports for every property, so recovery does not depend on which GM happens to be diligent. The same checks should run on the same schedule at every hotel, with results reported to ownership in one format. Leakage in OTA commissions, virtual cards, chargebacks, no-show fees and direct bill tends to repeat across hotels with similar systems.
For example (illustrative numbers only): an owner's first hotel has $3,000,000 in annual revenue and the second has $4,000,000, for a combined $7,000,000. If leakage is 1% at each, that is $70,000 a year across the portfolio. Hotels typically lose 3–12% of revenue to leakage; on the $4,000,000 hotel alone, that range is $120,000 to $480,000. Recovery handled the same way at both hotels lets you compare results and see which property needs attention.
Where does x·quic fit as you add hotels?
When you acquire a hotel, you inherit every past, current and future reservation plus whatever the prior operator mis-collected. x·quic recovers it from day one and shows every property on one dashboard, from 1 to 1,000+ hotels, with role-based views for GMs, controllers and ownership. The management companies page explains the setup.
Frequently asked questions
Should my second hotel be the same brand as my first?
It can simplify training, systems and reporting, but it is not required. Weigh the market fit of the brand against the cost of running two different systems.
Can I use equity from my first hotel to buy the second?
Many owners do, through a cash-out refinance or a partnership. The tax and lending implications vary, so confirm with your CPA, attorney and lender.
When should I hire a controller?
Many owners add a shared controller or outsourced accounting partner around the second or third hotel, when the owner can no longer review every close personally.
What should I check first after closing on the second hotel?
Open receivables, uncharged virtual cards, OTA invoices and inherited contracts. Those are the items most likely to hold money the prior operator never collected, and the easiest to lose track of during the transition.
Know what every hotel in the portfolio is leaking.
Run the free 1-year Profit Audit across your properties, including any hotel you are taking over, and see leakage by hotel, brand, and product in your own numbers. No cost, no commitment.